
INSURANCE FOR LABOUR HIRE AND RECRUITMENT COMPANIES
AMC INSURANCE PTY LTD
A QUICK OVERVIEW
Labour Hire and Recruitment Insurance protects you from the advice and services you provide to your clients. Also, from exposures to on-hired / temporary workers and contractors supplied to a Host Employer:
Professional Indemnity
Covers a breach of professional duty or services performed by employees. Also from advice from on-hired / temporary workers (e.g. Accountants, Real Estate Agents, Architects, Engineers, Managers, Nursing, etc. – to name a few.)
Public Liability (& Products)
Covers third party injury and third property damage from your business activities. Also, from on-hired / temporary workers performing work on behalf of a Host Employer.
Management Liability
From legal costs and damages to Directors & Officers from wrongful acts, employment disputes, and WHS/OHS defence costs.
Cyber Liability
For loss from data breaches, hacking response costs, ransomware, etc.
Business Insurance
Damage to assets owned by the business.
Workers Compensation
For injury to employees and workers
WHO NEEDS COVER
We find most new requests for insurance come from clients needing cover for:
- Placement of candidates in permanent positions
- Temporary placement of Employees and Contractors for the provision of On-Hired Services or On-Hired Medical Services
- Employment consulting services in the areas of
- occupational health and safety,
- human resources,
- human resources relations,
- human resources management,
- employment, outsourcing, psychological testing,
- reference checking,
- workplace assessments, and;
- careers counselling and/or change management
HOW COVER PROTECTS YOU
Examples of the types of risks that Professional Indemnity and Public Liability cover are:
- Written or verbal threats of legal action by a client from an actual or alleged negligence or failure in the services provided, or third-party injury/property damage
- Demands for financial compensation from your clients or third parties
- Actual legal demands or Court proceedings against your business from services provided
WHAT IS THE COST OF THE INSURANCE
It is too hard to offer an accurate indicative cost as many factors might impact premiums, for example:
|
Professional fees, gross revenue, and/or wages |
|
Staff numbers |
|
Types of services provided (e.g. Labour Hire, Recruitment Services, Permanent Placement, etc.) |
|
Nature of on-hired worker services for Labour Hire |
|
Policy limits |
|
Prior claims |
We find for small non-specialist Labour Hire providers offering White Collar on-hired workers annual premiums may start by ranging from $2,200 – $5,000 as a guide.
While for our Labour Hire businesses with Blue Collar on-hired workers should expect higher annual costs to start from $6,000 – $11,000.
INFORMATION NEEDED TO QUOTE
The documents we may need to quote for Professional Indemnity and Public Liability are:
| Proposal Form | this provides specific detail about your business operations that insurers use to assess your risk exposure |
| Addendums | these are infrequently required, but can be requested for specific occupation risk exposures |
| Renewal Declarations | we aim to shorten the amount of information required by our clients at renewal, however, it’ll still require key information like revenue, wages splits, etc. |
| Certificate of Currency | is only required as a new customer so that we can evidence and match the Retroactive Date for you. This ensures as broker we are providing the same retrospective cover as your outgoing insurer. |
| Claims History | is only required if there have been notifications or claims reported to an insurer. This is a document on your insurer letterhead and includes: date of loss, brief description, amounts paid by the insurer, amounts estimated (reserve) to be paid by an insurer |
| Terms of Business | this is the document you sign with your Host Employer and outlines the conditions of providing temporary workers to them. In line with the RCSA standard form document insurance companies will want to see an indemnity clause in your favour in the majority of your agreements. This is to protect your business from a Host Employer simply deferring each and every loss they incur to your business/insurer. |
Our labour hire and recruitment proposal form is available for download on this page as a PDF or we have an online form available too.
WE WILL MAKE SURE YOU HAVE THE RIGHT COVER
Over 50% of our customers are in the Labour Hire and Recruitment sector. It is sector we have supported for over a decade and remained committed to. This means we have a lot of firsthand experience placing appropriate insurance covers for our clients.
There are limited insurers providing cover to Labour Hire businesses, especially if you are in high-risk sectors (e.g. Blue Collar, Medical / Nursing, Mining, etc.) and it is important that a broker correctly outlines your risk exposure to the insurance company to avoid being declined a quote.
We have seen many cases, even with large insurance broking firms that should know better, where their Labour Hire clients have not had their policies correctly placed with an insurer. Some examples are:
- Other brokers not having the relevant on-hired / temporary worker extensions correctly negotiated with the existing insurer
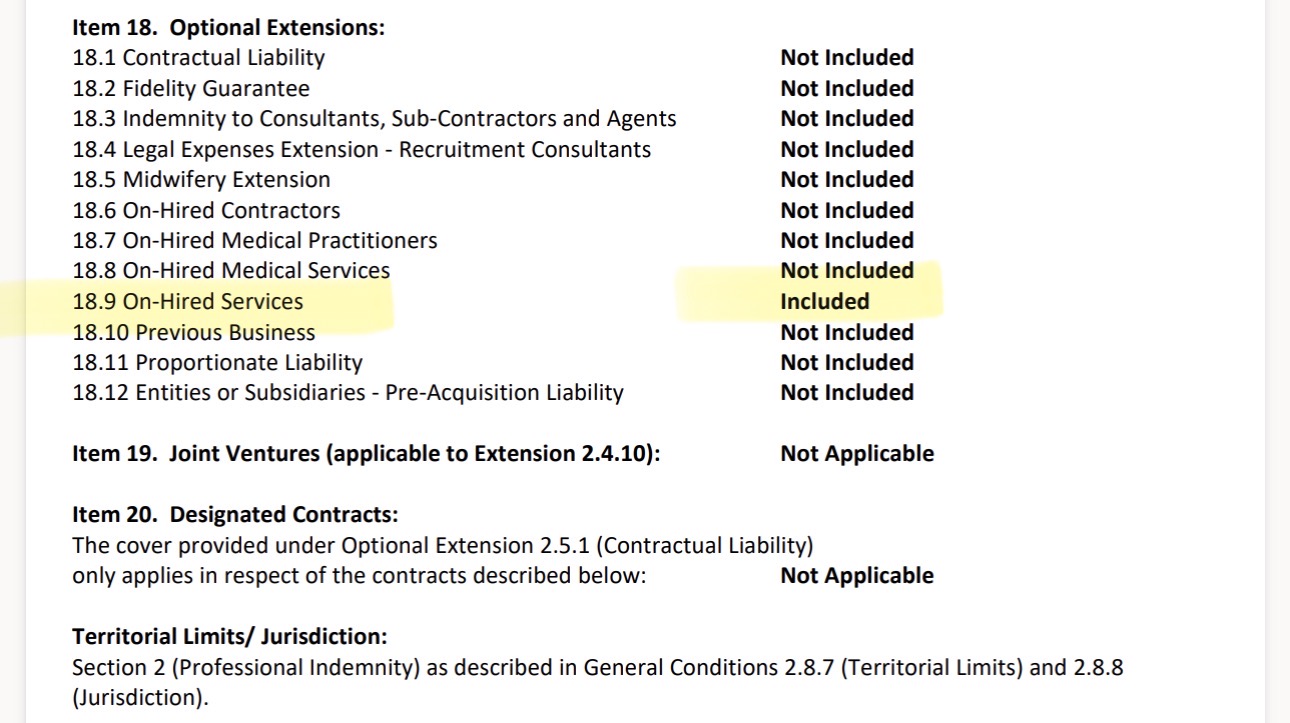
- Company names that require cover being missed and not listed on the insurance policy
- Incorrect Retroactive Dates meaning that past claims and liabilities cannot be claimed correctly against the policy
CLAIMS OVERVIEW
EXAMPLES OF LABOUR HIRE CLAIMS’ WE HAVE MANAGED FOR OUR CLIENTS
We have managed multiple claims over the years, but a few examples are:
- Forklift drivers causing damage to a Host Employers property resulting in $20,000 worth of repairs to roller doors
- Truck drivers being involved in an at-fault accident causing damage to a Host Employers vehicle and on-site assets resulting in recovery attempts from the Host Employer in excess of $1,000,000
- Locum medical doctors being held responsible for negligence in their advice resulting in legal demands in excess of $100,000
HOW WE SUPPORT CUSTOMERS DURING CLAIMS
We encourage and educate our clients that potential legal issues between you and a client (or third party) that may result in a claim still need to be notified to us and reported to your insurer.
A business that fails to report known claims or circumstances can result in an insurer limiting – or declining – cover. This mainly impacts Professional Indemnity / Management Liability / Cyber Liability policies due to the claims made and notified structure (please call or email Alex Conlon for more details).
In our experience, customers often worry reporting issues on a precautionary basis will impact their renewal premiums. However, in over 10 years of supporting labour hire and recruitment clients we have not had an insurer penalise renewal premiums in the absence of an actual claim. Once our clients have a better understanding on this, they gain more confidence in speaking with us when things go wrong.
Formal claims will require a lawyer or loss adjustor to be appointed by your insurer. Their initial role is to investigate and provide interim advice to your business (often on a reservation of rights basis). They report back to your insurer on the facts and provide guidance to them on policy coverage. The ultimate goal is to confirm indemnity is granted by the insurer and have a lawyer appointed to represent your business in defending the allegations, or, reaching a settlement, if appropriate.
INSURERS WE WORK WITH
The insurer we recommend can depend on several factors specific to your business and type of cover required.
PUBLIC LIABILITY & PROFESSIONAL INDEMNITY
Our Director, Alex Conlon, has found that working with About Underwriting Pty Ltd via their Lloyd’s of London binder, to be a great benefit to many of our new and existing labour hire clients, for blue collar and medical related risks. Some excellent results have been achieved by working directly with their Underwriting Manager, Jodie Banks, providing almost a decade of support to our clients.
Some specific challenges we have worked on to support the labour hire sector:
- Responding quickly to newly introduced insurance obligations enforced by the Queensland Government (Queensland Health) under their Contingent Workforce preferred supplier panel for the provision of Temporary and Contracted Workers.
- Finding solutions for Abuse / Molestation Liability Insurance for Labour Hire providers in the education sector in line with Department of Education Victoria’s coverage obligations as a result of vicarious liability to child abuse claims from workers.
Other Labour Hire insurer options are available and below are a few reasons they aren’t our first choice:
Inconsistent underwriting guidelines
An insurer that may be prepared to cover the exposure of Blue-Collar Labour Hire company supplying construction workers may also shy away from a relatively benign IT Labour Hire business.
Adjustment Premiums
Public Liability policies, like Workers Compensation policies, work off an estimated revenue/wages basis. This means at renewal an insurer will request the actual wages/revenue and may charge an increase/decrease in premium retrospectively.
We have heard stories from some prospective customers they decided not to change insurer/broker because their insurer was threatening to charge the adjusted premium, however, if they stayed with them, it would be waived.
Personally, we don’t support these kinds of business tactics from insurers. Whilst most of our clients appreciate the fact they have one premium bill to pay each year without any surprise or sudden retrospective charges.
Weak wordings
We find some insurers with wordings that we have decided include provisions that create vague and ambiguous risks for our clients.
An example, is many permanent placement insurers including an exclusion for claims arising from “placed personnel”.
To us, these exclusions read to limit the cover unnecessarily; and, if it wasn’t the insurers intention to limit cover then why include the exclusion in the first place.
Poor claims handling
Many claims run smoothly. Some have claims complex issues to manage and may require a “hands-on” approach to keep things on track from time-to-time.
However, in very (very) rare cases everything to do with a claim goes wrong… but, when we feel these issues have occurred because of an insurer and underwhelming procedures and processes, we will draw a line as broker and say to clients we are not prepared to work with those insurance markets.
MANAGEMENT LIABILITY
- About Underwriting Pty Ltd – have a solid policy wording that blends well with their recruitment package. For smaller businesses their minimum premiums may be cost prohibitive.
- Berkley Insurance Australia Limited – are a primary insurer we have worked with for a long time. They have a good wording, competitive premiums and good service standards. We have had issues post-claims at renewal with what we have felt were unfair premium loadings and imposed excesses, even for long term clients.
- Chubb Insurance Australia Limited – offer a quality wording with some unique benefits (like a broad Crime extension, Kidnap & Ransom, etc.). Unfortunately, their standard excesses are much higher than other insurers in the market as are premiums.
- AIG Insurance Limited – again, offer a good wording back by unique extensions. For Labour Hire risks the exposure to Occupational Health & Safety Defence Costs cover means the policy becomes cost prohibitive.
- Hutch Underwriting Pty Ltd – are a newer entrant to the market who we are investigating as a possible, well priced solution, for clients. There is also a benefit of some unique market extensions and generally lower excesses.
CYBER LIABILITY
- 360 Cyber – this is a primary insurer we like to use. We find that their wording is clear and concise in their inclusions/exclusions. The premiums are fair and the insurer has worked to expand several extensions (like Directors & Officers Liability extension, NIL excesses in some cases; often at no additional charge).
- Chubb Insurance Australia Limited – we find that the Chubb wording is one of the more complex to interpret notwithstanding the advertised benefits. Premiums are quite reasonable as are excesses. An advantage to Chubb is the ability to offer higher policy limits up to $5M without additional underwriting information.
- Coalition – we consider has a unique market offering through their client-oriented portal providing insights and recommendations to guide customers on potential security issues and vulnerabilities from their online presence.
- About Underwriting Pty Ltd – have access to their own binder and open market insurer options, for more complex risks.
BUSINESS INSURANCE
- Vero Insurance – through our connection to the AUB Group we have the benefit of a unique Austbrokers extension that means several strong benefits are included to customers without needing to charge additional premiums. Vero have consistently provided very high service standards and quick approvals on straight forward claims (i.e. think damaged laptops dropped down a flight of stairs, or a non-violent theft that resulted in stolen property from the office during business hours… yes, we find that happens more often than you think, especially for employees bicycles!)
- 360 Commercial – similar to Vero they provide several default extensions. Previous claims experiences with 360 have offered quick response times. Higher standard excesses of up to $1,000 compared to some other insurers still prepared to offer $250 or $500.
OUR POINTS OF DIFFERENCE AS A SPECIALIST LABOUR HIRE INSURANCE BROKER
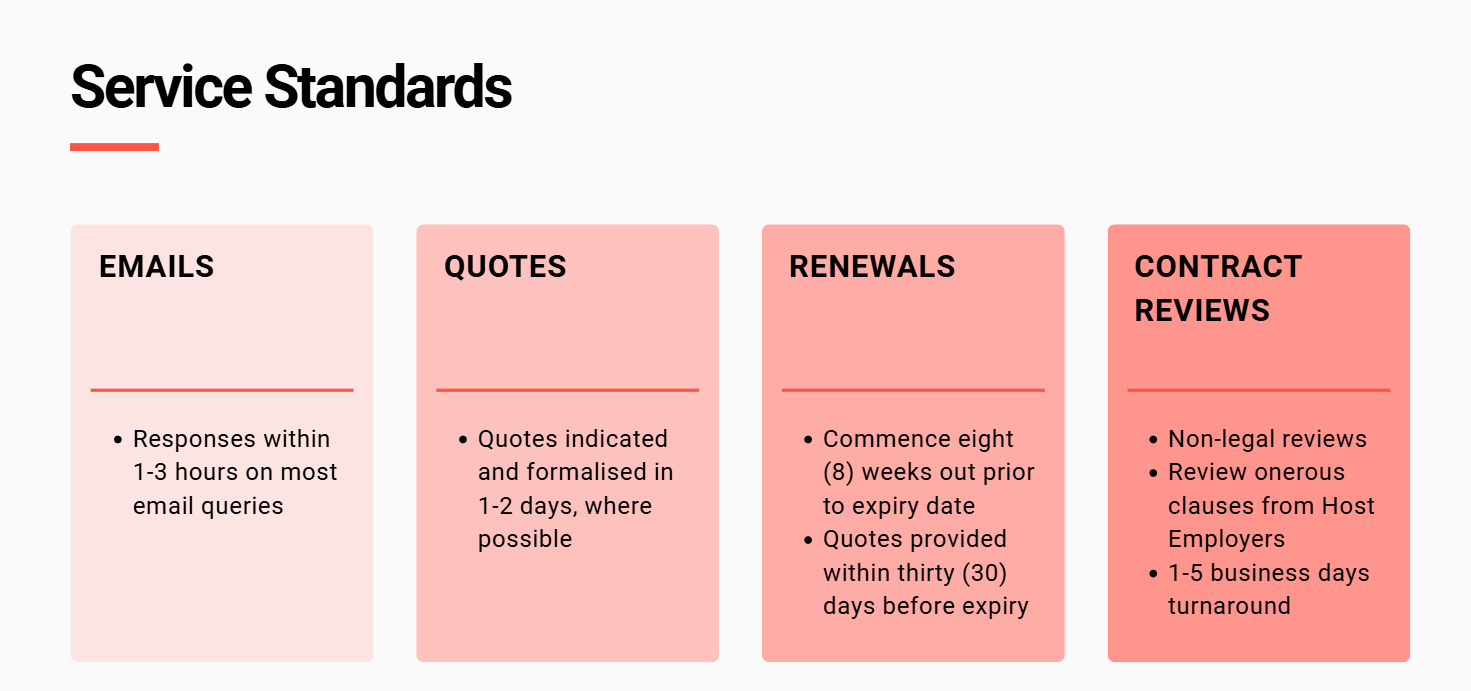
- A primary point of contact year-on-year via our Director, Alex Conlon and support from Monica Cook as our Business Development Manager
- Fast response times (most queries are actioned within 1-3 hours)
- An early renewal review process early (aiming for 8 weeks prior to expiry); quotes are provided within thirty (30) days from the expiry date, where possible (not days out from your expiry date!)
- New quotes aim to have indicative premiums provided within 1-2 business days
- Non-legal contract reviews for non-standard Terms of Business from Host Employers to highlight major issues that might impact insurance coverage (completed within 1-5 business days)
- Policy comparisons can be provided between our quote and other brokers/insurers highlighting differences in cover
TESTIMONIALS & KIND WORDS
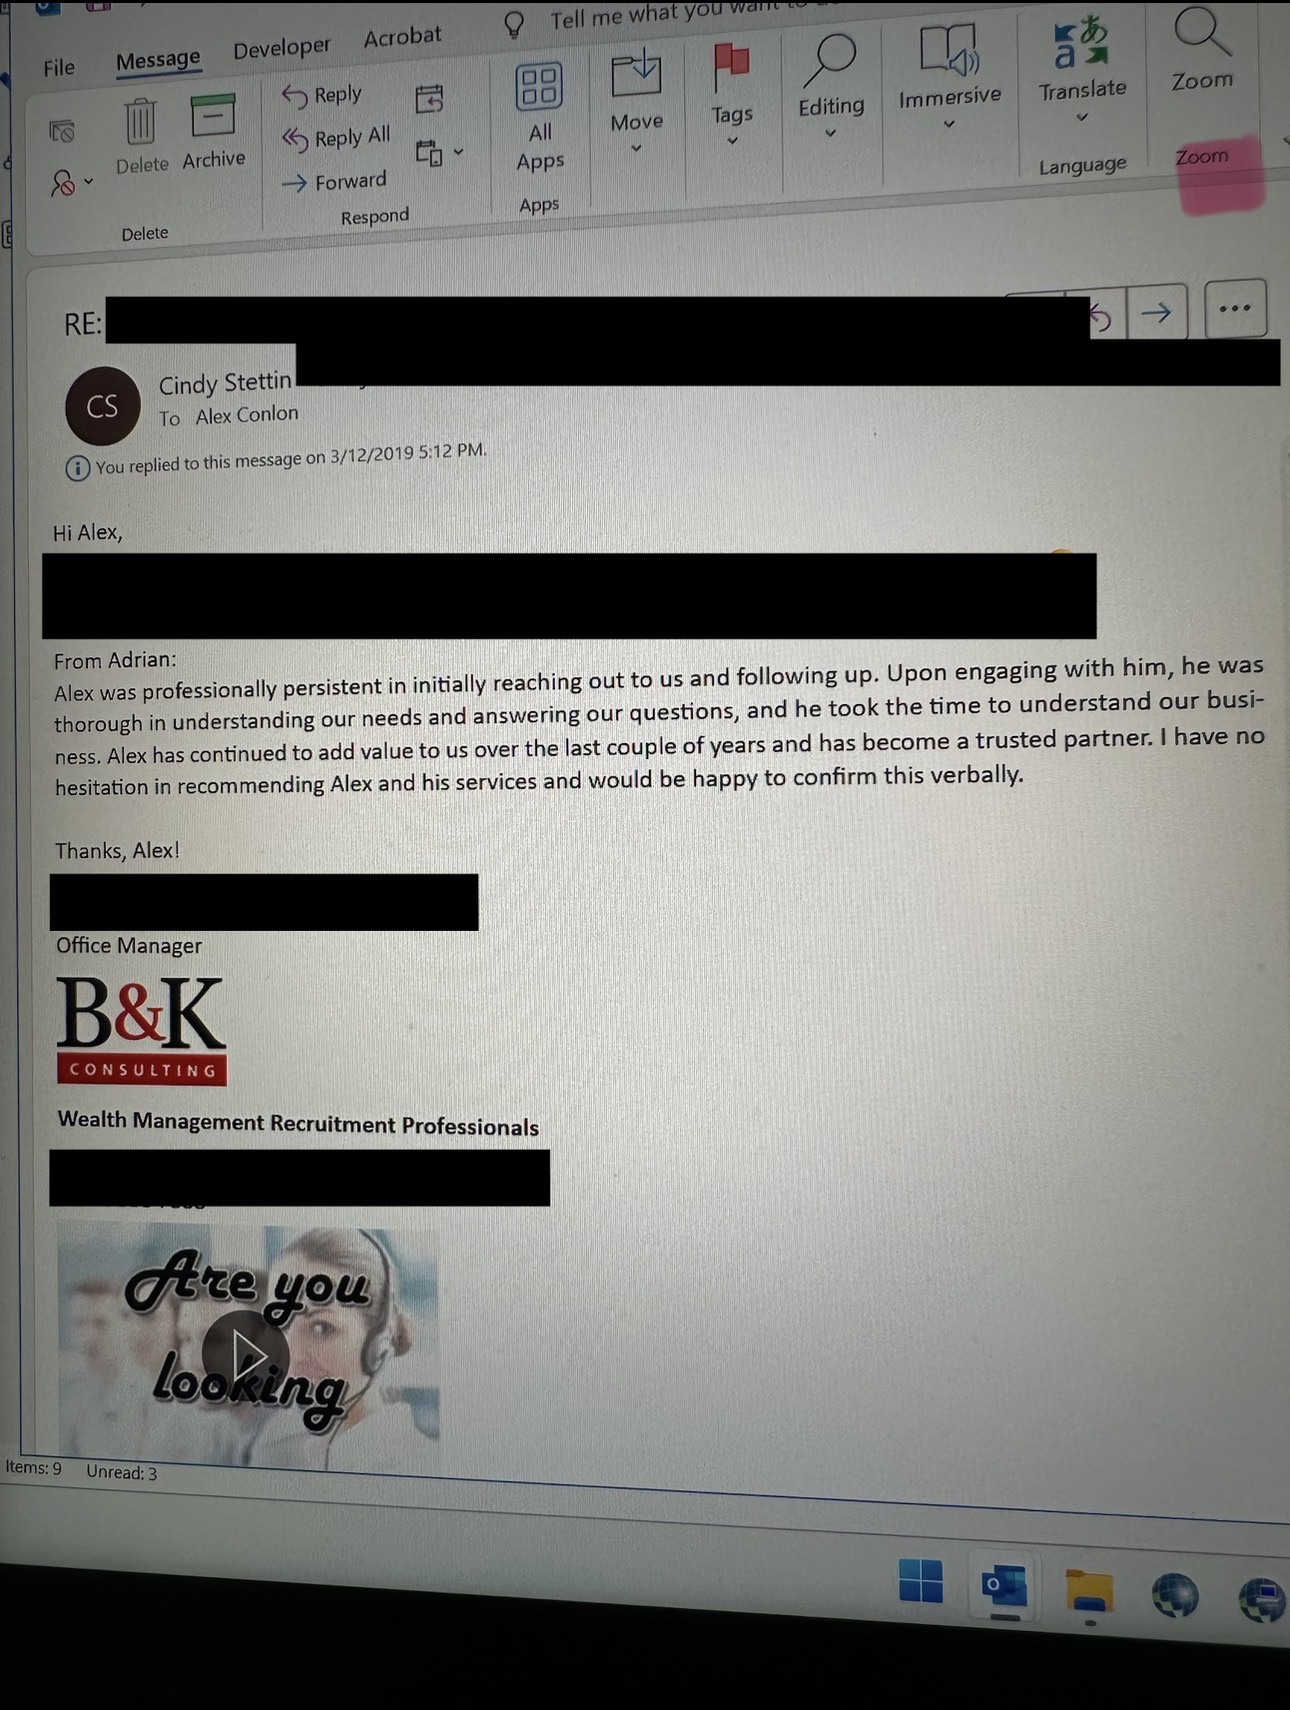
“Alex was professionally persistent in initially reaching out to us and following up. Upon engaging with him, he was thorough in understanding our needs and answering our questions, and he took the time to understand our business. Alex has continued to add value to us over the last couple of years and has become a trusted partner. I have no hesitation in recommending Alex and his services and would be happy to confirm this verbally.”
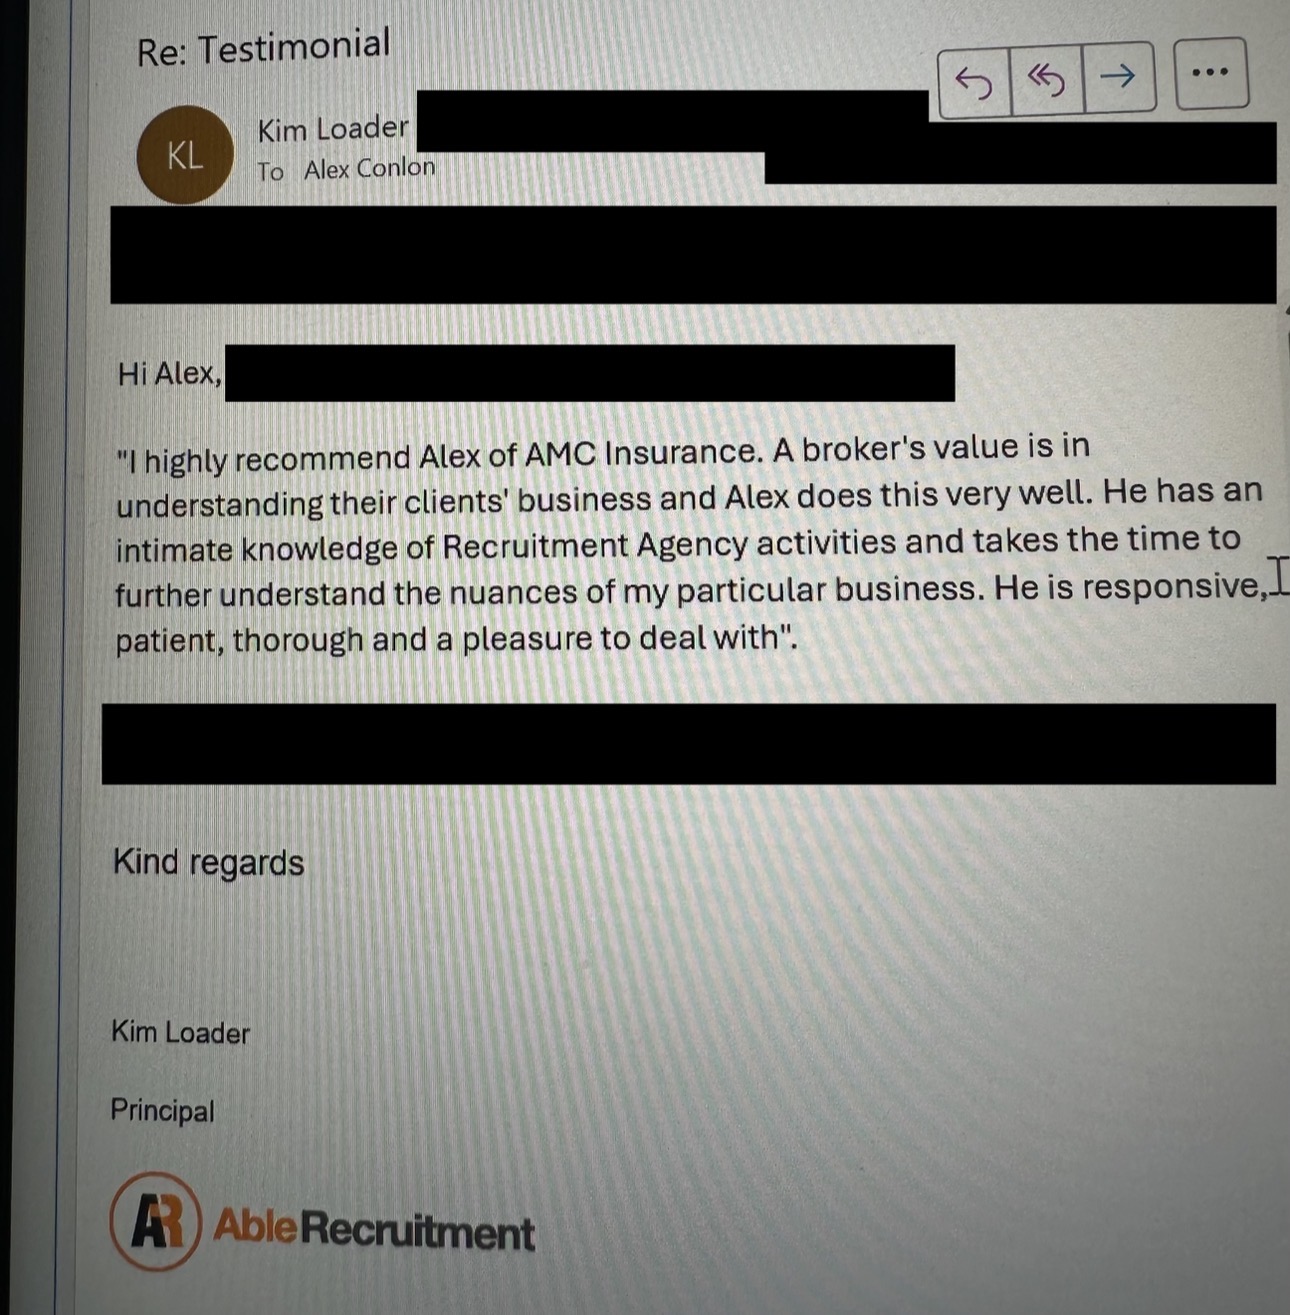
“I highly recommend Alex of AMC Insurance. A broker’s value is in understanding their clients’ business and Alex does this very well. He has an intimate knowledge of Recruitment Agency activities and takes the time to further understand the nuances of my particular business. He is responsive, patient, thorough and a pleasure to deal with”
- Other kind comments from outgoing employees from current clients include:
“I also wanted to take the opportunity to thank you for all your help and guidance over the past few years. I’ve learned an enormous amount from working with you and have always genuinely appreciated how helpful and generous you have been with your time and knowledge.”
Alex Conlon
Director | M: 0409 092 947 | E: alexc@abterrace.com.au
TO OBTAIN INSURANCE FOR LABOUR HIRE AND RECRUITMENT PLEASE COMPLETE AND RETURN THE BELOW FORM TO: ALEXC@ABTERRACE.COM.AU
TO OBTAIN PROFESSIONAL INDEMNITY AND PUBLIC LIABILITY QUOTE PLEASE COMPLETE AND RETURN THE BELOW FORM TO: ALEXC@ABTERRACE.COM.AU
Alex Conlon
Director | M: 0409 092 947 | E: alexc@abterrace.com.au
Alex Conlon established AMC Insurance Pty Ltd in 2016 and is a Qualified Practicing Insurance Broker (QPIB).
He supports various industry segments with specialisations in Labour Hire, Recruitment, Manufacturing (Toys), and financial lines products (Professional Indemnity, Management Liability, Cyber Liability).
His insurance career began in 2008 as a commercial insurance underwriter within the Suncorp Group Limited. Transitioning to work with multi-national broker Marsh Pty Ltd in their financial lines broking team whilst completing his Diploma of Insurance Broking in 2011.
In 2015 he won the regional (SA/NT) Young Professional Broker of the Year award, prior to commencing a senior role with a nationally operating broker specialising in Architects & Engineering risks.